100 stars - Brody is an absolute diamond. His knowledge and service are second to none, and he genuinely cares about the people he works with. We'd applied to a major bank ourselves and were facing endless delays and a lack of communication. We called Brody for help and within days he had completely turned our situation around, securing us a better loan than the bank was offering in about 10% of the time it took them. Can't recommend him highly enough!
Cooroy mortgage broker, ten minutes down the road
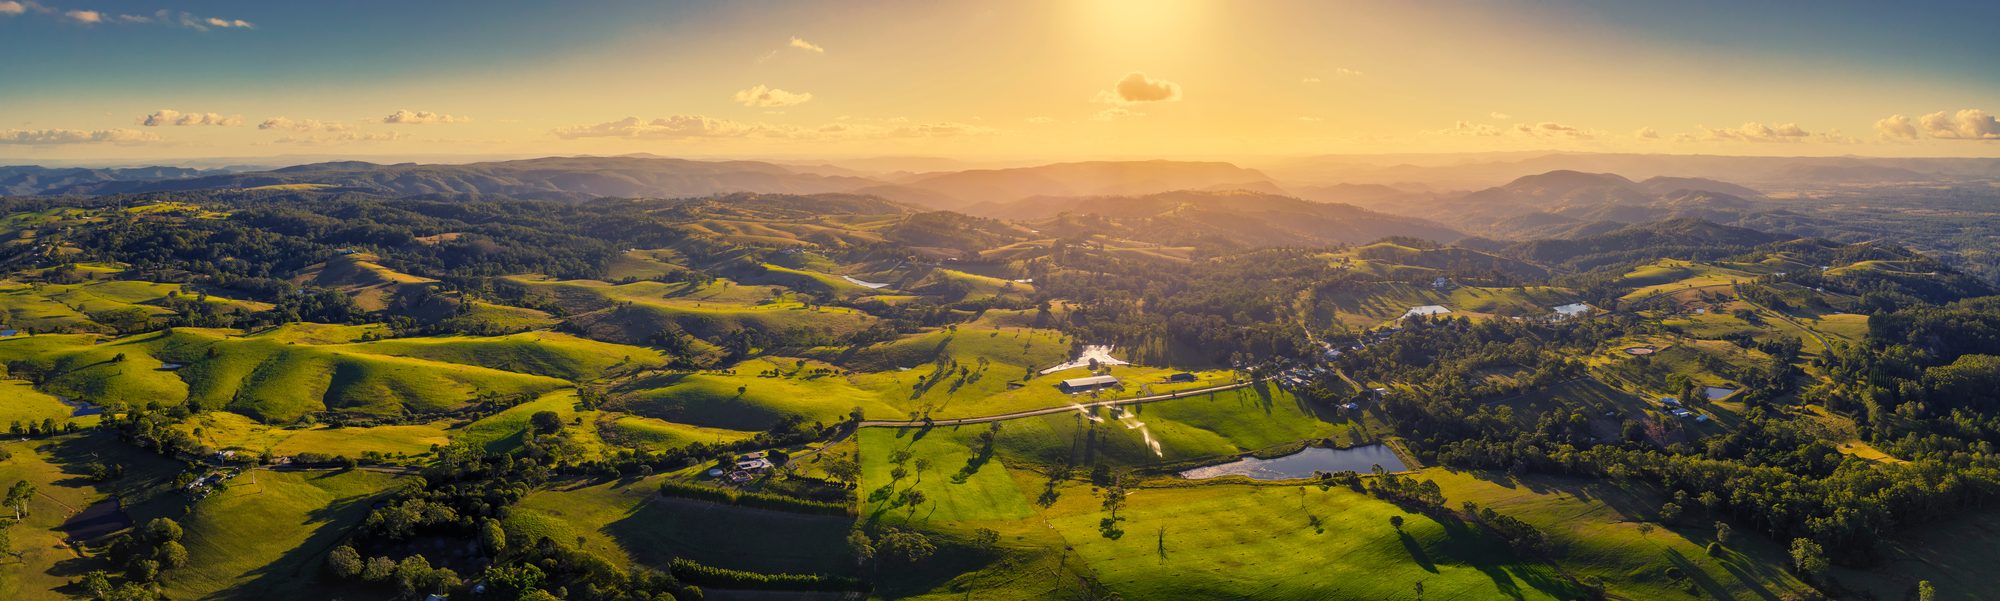
Cooroy is the hinterland town that actually works as a town — real main street, train station, schools, industry, and everything from modest town blocks to serious acreage up on Cooroy Mountain.
By Brody Baker, Credit Representative 531935 & 545794 · Market figures reviewed September 2026
Fundi Finance is at Eumundi, about ten minutes down the road. Brody writes loans across Cooroy, Cooroy Mountain, Lake Macdonald, Black Mountain and Tinbeerwah regularly, and knows where the lending pinch points are in each of them.
The Cooroy market
| Measure | Cooroy |
|---|---|
| Median house price | ~$1,195,000 |
| Annual capital growth | ~14.6% — strong |
| House sales (12 months) | ~93 |
| Average days on market | ~35 days |
| Median rent (house) | ~$800/week |
| Gross rental yield | ~3.6% |
| Unit sales (12 months) | ~10 — very thin |
| Transport | Train station on the North Coast line |
CoreLogic-sourced figures for the twelve months to mid-2026, rounded. Broader data sources report a lower average around $930,000 by including a wider property mix. Indicative only — not a valuation.
What's specific about lending in Cooroy
First home buyers: build, or buy at the lower end
Because the median clears both the 5% Deposit Scheme cap ($1m) and the Queensland established-home duty concession cut-off ($800,000), first home buyers in Cooroy have three realistic plays:
- Buy at the lower end — under $1m keeps the 5% Deposit Scheme alive; under $800,000 keeps some duty concession too.
- Build. This is the strongest one. Queensland's duty exemption on new homes and vacant land has no price cap at all, and the $30,000 First Home Owner Grant applies to eligible new homes under $750,000. Land-and-build in Cooroy can access help that an established purchase simply can't.
- Look at units — cheaper entry, though see the warning below.
Full breakdown on the QLD first home buyer grants page.
The unit market is very thin
Around ten unit sales in a year. That's not much for a valuer to work with, which makes unit valuations harder to support. Some lenders also restrict small units, typically under 40–50m² of internal living area. Units here are absolutely financeable — but lender choice matters, and an upfront valuation before going unconditional is worth the delay.
Acreage on the mountain
Cooroy Mountain, Black Mountain and out towards Lake Macdonald bring the usual acreage rules: up to about 2 hectares is standard residential lending with full market access, past that the panel narrows and deposits often rise. Tank water and septic are normal and rarely an issue on their own. See acreage and rural home loans.
You can check zoning, overlays and approvals yourself for free before you offer. Cooroy is Noosa Shire, so use Noosa Council's mapping and Site Information Report — Sunshine Coast Council's Development.i doesn't cover it.
The rail station is a genuine lending positive
Eumundi and Pomona have stations on the same line too, but Cooroy and Nambour get noticeably more services. That supports both owner-occupier demand and rental demand, and it's part of why Cooroy has held growth well.
You've got more time here than in Nambour
About 35 days on market versus roughly 16 in Nambour. That's a materially different buying experience — more room to arrange finance, more room to negotiate, less pressure to have everything pre-arranged before you bid. Pre-approval is still worth having, just less of an absolute necessity to compete.
General information only — it doesn't take into account your objectives, financial situation or needs. Market figures are indicative, drawn from publicly available data as at September 2026, and are not a valuation. Lender policies and scheme details change regularly; please confirm before acting.
Cooroy home loan questions, answered
Is there a mortgage broker in Cooroy?
Fundi Finance covers Cooroy from Eumundi, about ten minutes south. Brody lives in the hinterland and regularly writes loans across Cooroy, Cooroy Mountain, Lake Macdonald, Black Mountain and Tinbeerwah — town properties, acreage, first homes and refinancing. In person locally, or by phone and video.
What's the median house price in Cooroy?
Around $1,195,000 on CoreLogic data for the twelve months to mid-2026, with annual growth near 14.6%. Roughly 93 house sales in that period, averaging about 35 days on market. Some broader sources report closer to $930,000 by including a wider property mix. House rent sits around $800/week for a gross yield near 3.6%.
Can first home buyers buy in Cooroy?
Yes, but the ~$1,195,000 median sits above the $1,000,000 cap under the 5% Deposit Scheme, so a median-priced house won't qualify for the 5% deposit no-LMI route. You'd need to target the lower end, consider units, or build. The Queensland duty concession on established homes also stops above $800,000 — but the separate new-home and vacant-land exemption has no price cap at all, which makes building the strongest scheme pathway here.
Does Cooroy have a train station?
Yes — on the North Coast line, with services south towards Nambour, the Sunshine Coast and Brisbane. Eumundi and Pomona also have stations on the line, but Cooroy and Nambour get more frequent services.
Can you get a loan on acreage at Cooroy Mountain?
Yes. Up to about 2 hectares is generally standard residential lending with the full market available. Past roughly 2 ha the panel narrows and some lenders lower the maximum LVR, meaning more deposit. Larger holdings around Cooroy Mountain, Black Mountain and Lake Macdonald stay financeable through lenders comfortable with rural-residential property — land size, zoning and any income off the land decide who'll look at it.
Is Cooroy a good investment?
Growth has been strong — around 14.6% over the twelve months to mid-2026, high for the region. Yield is more modest at roughly 3.6% gross, with house rent near $800/week. So it suits capital growth over income. If yield is your priority, Nambour returns closer to 4.2% at a much lower entry price.
Is it hard to finance a unit in Cooroy?
It needs more care. Only about ten units sold in the year to mid-2026 — a very thin market, which makes valuations harder to support. Some lenders also restrict small units, typically under 40–50m² internal. Financeable, but lender choice matters and an upfront valuation is worth considering.
How long do houses take to sell in Cooroy?
About 35 days on average to mid-2026 — considerably slower than Nambour's ~16. That means more time to sort finance and more room to negotiate. Pre-approval still helps, but it's less critical to competing than it is in faster markets nearby.
How much deposit do I need?
On a town block, normal rules: 20% avoids LMI, less is possible with LMI payable. The 5% Deposit Scheme route only works under the $1,000,000 Sunshine Coast cap — which excludes a median Cooroy house but covers the lower end. On acreage past about 2 ha, expect 20% or more.
Cooroy vs Eumundi vs Noosa?
Cooroy is the larger, more practical town — bigger centre, train station, schools, industry, and everything from modest blocks to mountain acreage. Eumundi is smaller, more lifestyle-driven, generally dearer and with a much wider spread of values. Noosa is coastal and a big step up again in price. Cooroy usually offers the most housing variety and the best transport of the three.
Local broker or my own bank?
A bank offers only its own products under one policy set. Cooroy's mix — town blocks, thin unit stock, mountain acreage — means properties often fall outside one lender's policy while sitting fine within another's. A broker checks which lenders suit the property before anything is submitted. Generally paid by lender commission rather than by you.
What Brody's clients say
Working with Brody was hands-down the best decision we made during our home buying process. From our first conversation he was professional, knowledgeable, and genuinely invested in helping us secure the best possible loan. He was incredibly responsive and proactive - always one step ahead - found us a great rate, helped us understand all our options, and even followed up after closing to make sure everything went well. Honest, efficient, and truly has your best interest at heart. Highly recommend!
Excellent service, great communication. I could not recommend Brody more!
A local mortgage broker across the Sunshine Coast & beyond
Have a chat
Send through the address of anything you're looking at, or a rough outline of your situation, and Brody will come back with a straight answer — what you could borrow, which schemes actually reach in Cooroy, and whether the property itself is going to narrow your lender options.